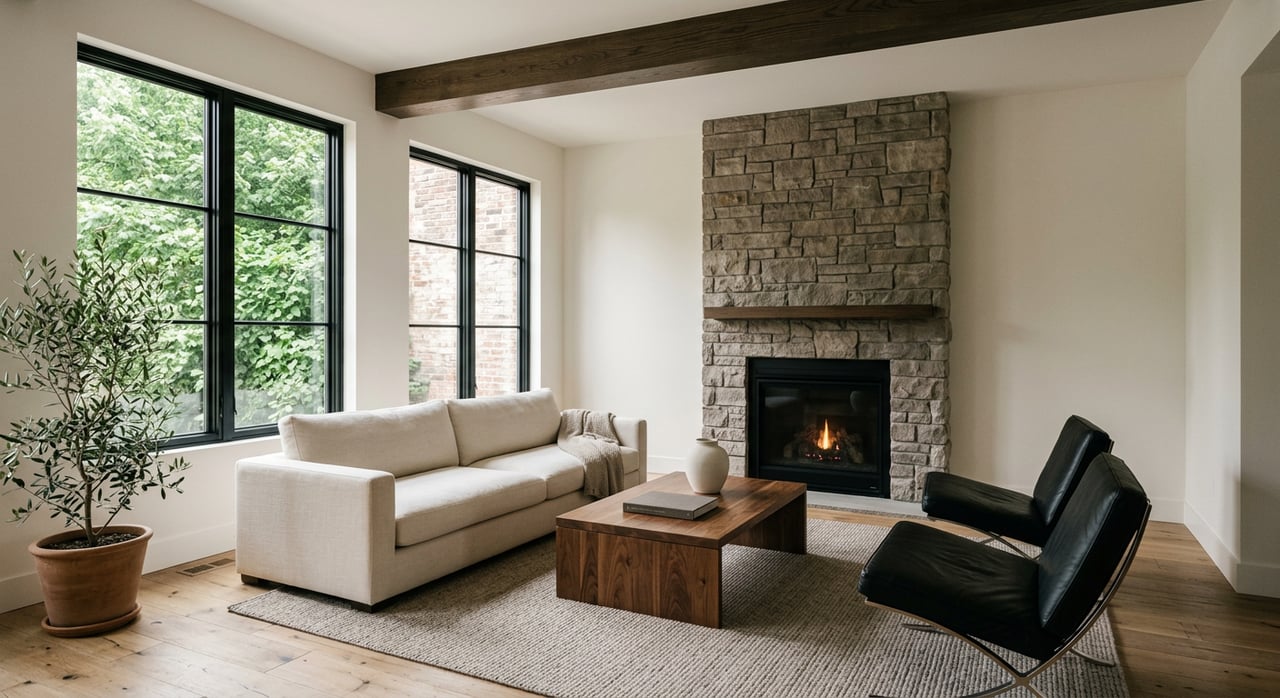
Midtown Condos vs Homes: How To Decide
March 5, 2026
March 5, 2026
Torn between a sleek Midtown condo and a classic intown home? You are not alone. Midtown’s energy, walkability, and culture make the choice exciting, but the details matter. In this guide, you will compare lifestyle, costs, rules, financing, taxes, and resale patterns so you can choose with confidence. Let’s dive in.
Midtown in this article refers to the Midtown Improvement District, a roughly 120‑block core along Peachtree Street that includes Piedmont Park and is within the City of Atlanta in Fulton County. You can see a clear map and overview on the Midtown Alliance site’s description of where Midtown is.
Midtown is a dense live‑work neighborhood with cultural institutions, restaurants, and MARTA access. The Midtown Alliance reports roughly 20,000 residents and a much larger daytime workforce, which helps explain demand for walkable homes and short commutes. Explore the district context on the Alliance’s About Midtown page.
If you are comparing housing types, the mix matters. In ZIP code 30309, which covers much of Midtown, multi‑family housing makes up more than 80 percent of units and renting is common, which is why condo inventory and HOA dynamics play an outsized role in buyer decisions here. You can review ZIP‑level housing mix on 30309’s profile.
If you want walkability, a quick commute, amenities, and low‑maintenance living, a condo in a Midtown tower or mid‑rise can be a strong fit. Many buildings offer concierge or security, gyms, pools, and lounge spaces. You lock your door and go. The tradeoff is less control over exterior design and building policies, plus the possibility of special assessments when big capital projects arise.
If you prefer privacy, outdoor space, and more control over improvements, a single‑family home or a fee‑simple townhome in nearby intown neighborhoods may be the better fit. Intown enclaves like Ansley Park, Sherwood Forest, and Loring Heights offer a different pace, with fewer but often larger properties than Midtown’s condo towers. You take on more maintenance and planning, but you gain flexibility over landscaping, additions, and long‑term ownership.
In a Georgia condominium, you generally own your interior unit and share ownership of common elements with other owners. The association typically maintains the building exterior, roof, elevators, hallways, and other common systems, while you handle the interior of your unit. These responsibilities are outlined in Georgia’s condominium statute, and the exact split is controlled by each building’s documents. Review the governing rules in Georgia Code 44‑3‑105 and confirm details in the building’s declaration and bylaws.
In a single‑family home or most fee‑simple townhomes, you own and maintain the structure and the land. A neighborhood HOA, if one exists, usually maintains only shared amenities such as an entrance, pool, or green space. The benefit is control and freedom. The tradeoff is that exterior repairs, roofs, and yard work sit on your to‑do list and budget.
In Midtown towers, monthly HOA dues commonly cover exterior maintenance, building envelope insurance for common areas, elevator service, shared HVAC or boiler systems, landscaping, security or concierge, trash, pool and gym upkeep, and reserves for future capital projects. Some buildings include certain utilities or high‑speed internet in the dues. Always review the current budget and line items to know exactly what is included.
Monthly amounts vary widely by building type and amenity level. As a general Midtown snapshot, smaller walk‑ups can land in the low $200s to $400s per month. Mid‑range high‑rises often run around $700 to $800. Full‑service luxury towers with extensive amenities can run from $1,000 to $2,500 or more per month. Ask for the HOA disclosure and recent budgets for any building you are considering so you can compare apples to apples.
If you plan to finance a condo, lenders often complete a condo project review to confirm the building meets eligibility standards. Fannie Mae’s Condo Project Manager outlines project criteria, and issues like a high investor ratio, excessive commercial space, pending litigation, or insufficient reserves can affect conventional financing options. Learn how lenders evaluate projects in Fannie Mae’s Condo Project Manager.
FHA and VA loans also have building approval processes. A condo that is not on the approved list may still be financeable, but you will face extra steps or need alternative loan products. You can read FHA program context on HUD’s FHA INFO page. In Midtown, boutique conversions or older associations can be non‑warrantable, while professionally managed towers are more likely to meet agency expectations. Always confirm a building’s status with your lender before you write an offer.
Property taxes in Fulton County are based on assessed value, with multiple taxing authorities setting millage rates. Homestead exemptions can reduce tax bills for owner‑occupants. For a specific address, request the seller’s most recent tax bill and run the county estimator to model current millage inputs. Use the Fulton County tax estimator to get parcel‑specific numbers.
For insurance, condo owners typically carry an HO‑6 policy that covers interior finishes and personal property, while the association carries a master policy for the building’s common elements. Confirm the master policy type and the association deductible, since that affects how you structure your HO‑6 coverage. For single‑family and fee‑simple townhomes, you will carry a standard homeowner’s policy that covers the structure and lot.
Recent data shows attached and detached homes have moved differently. In a January 2026 Georgia market snapshot based on FMLS data, the median for attached units such as condos and townhomes was about $340,000, while detached single‑family homes were around $406,000. You can see the latest metro figures in this January 2026 market report. Remember that Midtown is a micro‑market: luxury towers and specific buildings can perform differently than metro medians.
Analysts also note that in some recent periods the condo market inside the core softened relative to single‑family due to higher tower inventory, while select luxury product bucked the trend. For perspective on how supply and demand vary by submarket and product type, review local commentary on intown trends and strategy. The takeaway for you is simple: use building‑level comps and association data for pricing and resale expectations, not just citywide medians.
Condos: Professionals who want walkability, quick access to Midtown’s employers and cultural venues, and reduced maintenance often favor condos. Downsizers who value amenities and a “lock and leave” lifestyle do as well. Midtown’s mix of residents and daytime workers, plus transit access around Peachtree and MARTA stations, supports this profile. Explore the neighborhood context on the Midtown Alliance overview.
Single‑family and townhomes: Buyers who prioritize private outdoor space, flexibility for future improvements, and a longer time horizon for land‑driven appreciation often look to nearby intown neighborhoods with detached homes or fee‑simple townhomes.
On a national level, the buyer pool has skewed older in recent years and first‑time buyers have made up a smaller share, which can influence which property types are most competitive in urban cores. See the high‑level shifts in the NAR 2025 Profile of Home Buyers and Sellers.
To compare a Midtown condo and an intown home, add up your total monthly carrying cost for each option. For a condo, that is principal and interest plus HOA dues, property taxes, and HO‑6 insurance. For a home or fee‑simple townhome, that is principal and interest plus property taxes and homeowner’s insurance. Because Midtown condo HOAs can range widely, the HOA line can outweigh other cost differences. Ask your lender to produce side‑by‑side estimates and pair those with the seller’s most recent tax bill and the association’s current budget.
Use this section as your due‑diligence roadmap.
When you are ready to compare real options, get a tailored, building‑ or neighborhood‑level analysis. For a concierge approach backed by data and premium presentation, connect with Catherine Newsome for a custom side‑by‑side that fits your goals.
November 19, 2026
November 12, 2026
November 5, 2026
October 29, 2026
October 22, 2026
October 15, 2026
October 8, 2026
October 1, 2026
September 24, 2026
Whether you're buying or selling, Catherine Newsome is committed to guiding you through every step of the real estate process with integrity, passion, and personalized service. Let her help you find your dream home or sell your property for the best price—your goals are her priority!